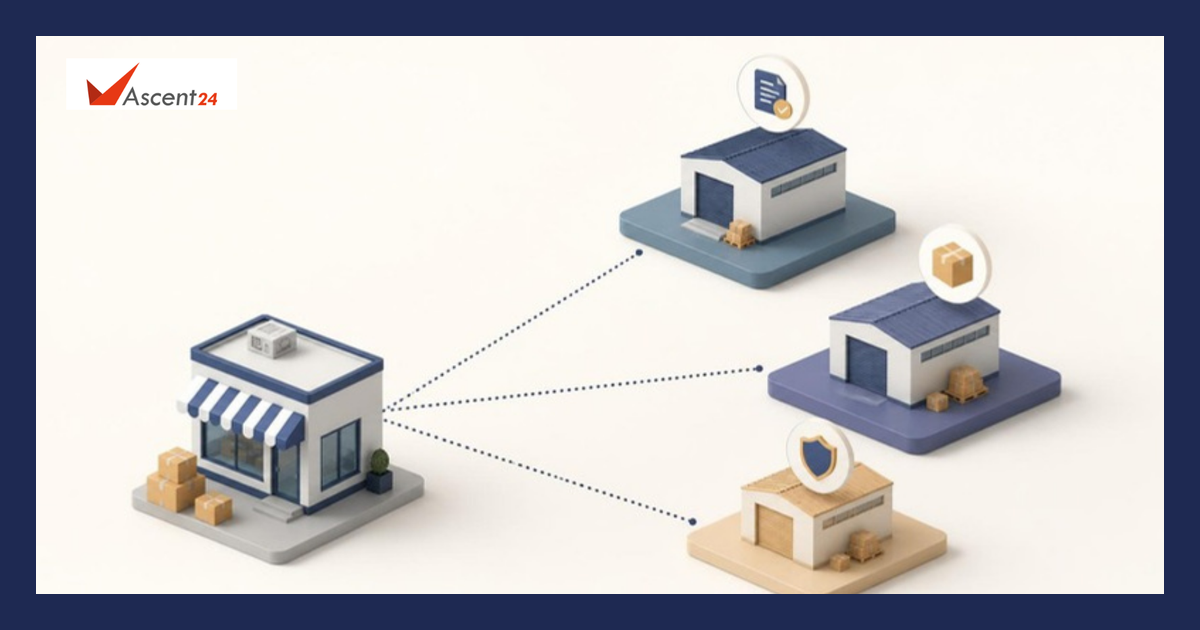
Today, selling from a marketplace warehouse in another state usually means a separate GST registration with a place of business there. That is the cost this proposal tries to remove.
What has been proposed?
According to the GST Council's 57th meeting press release and the Finance Ministry's FAQs on the recommendations, the scheme is optional and works like this:
- You apply in FORM GST REG-01 for a state where you have no physical presence, choosing the Rule 14B option.
- You declare the e-commerce operator's (marketplace's) warehouse in that state as your principal place of business. Other warehouses of that operator in the state can be added as additional places of business.
- The application goes to the marketplace, which must give consent within 7 working days. Without consent, the application is treated as rejected.
- Verification, including biometric Aadhaar authentication, happens in your home state, and registration is then granted electronically.
Who is it meant for?
The FAQs list these conditions:
| Condition | What it means in practice |
|---|---|
| Goods sold only through e-commerce operators that collect tax at source (TCS) under section 52 | Sales outside these platforms, including your own website, can't go through this registration |
| Output tax on supplies to registered buyers (B2B) of no more than ₹2.5 lakh a month | Mostly B2C sellers. Stock transfers to your own GSTINs don't count |
| A regular registration in your home state | You need an existing home-state GSTIN |
| Marketplace consent | The platform decides whether its warehouse can be used |
| One registration per state against your PAN | No multiple registrations in the same state under this scheme |
If you are registered in your home state only under the existing Rule 14A option, the FAQs say you must withdraw from it (FORM GST REG-32) before applying under Rule 14B.
What would stay your responsibility?
Registration gets simpler, but compliance does not go away. Each extra state is still a separate GSTIN with its own returns. The FAQs also say:
- Books of account and records for every Rule 14B registration must be kept at your principal place of business in your home state, and produced when the state officer asks.
- If the marketplace withdraws consent, you have 30 days to file FORM GST REG-14 and change the address. If you don't, the registration is cancelled automatically.
- If your home-state registration is cancelled, the Rule 14B registrations go with it.
So the real question for a seller is not "Can I register?" but "Can my systems handle stock, invoices and returns across several GSTINs without errors?"
Five things to prepare now
- Check your sales mix. List your monthly B2B output tax and how much you sell through marketplaces versus your own site. If B2B tax regularly goes above ₹2.5 lakh a month, this scheme may not fit.
- Shortlist states using data. Pick states where your orders already ship and slow delivery is costing sales.
- Ask your marketplace early. Consent is the platform's call. Ask how it plans to handle Rule 14B requests.
- Track stock by state. Each state's stock belongs to a separate GSTIN, so you need clean records of transfers, sales and returns per state.
- Plan accounts per GSTIN. Returns and reconciliations multiply with each state. Agree the filing load with your tax adviser first.
Where software helps, and where it doesn't
Software won't decide whether you qualify; that's for your tax adviser once the rule is notified. It helps with the daily work: tracking stock by warehouse and state, invoicing from the right GSTIN and matching marketplace settlements to your books. Our guide to omnichannel inventory software for retailers explains how to keep stock accurate across locations, and custom ERP vs SAP vs Tally compares system options.
BestERP, Ascent24's ERP and CRM platform, includes multi-warehouse inventory and GST-ready billing, and Ascent24 also builds custom integrations between marketplaces, inventory and accounting.
Planning to sell in more states? Tell us how you sell today and we'll help you map the system changes. Talk to Ascent24 on WhatsApp, call +91 96558 70024, or email info@ascent24.io.
FAQs
Is Rule 14B in force now?
No. The GST Council has recommended it. It applies only after the government notifies the rule, and the press release says only the notified law has legal force.
Can I use this registration for sales on my own website?
No. The FAQs say the registration is only for supplies of goods through e-commerce operators that collect TCS, so other supplies can't be made under it.
Do I need to display my GSTIN at the marketplace warehouse?
No. The FAQs say sellers under this scheme don't need to display it there.
Sources
- PIB, 8 October 2026: Recommendations of the 57th Meeting of the GST Council
- GST Council: FAQs on recommendations made in the 57th GST Council meeting (simplified registration for e-commerce sellers, pages 8 to 11)